October 2026
The Gen X Playbook

Gen X at the Peak: Why High Earners Are Feeling the Squeeze

Gen X is in its peak earning years and still carries the highest household spending of any generation, but PYMNTS Intelligence data shows that seven in 10 now live paycheck to paycheck, up from six in 10 in 2021. The generation that should have the most cushion is running out of it.

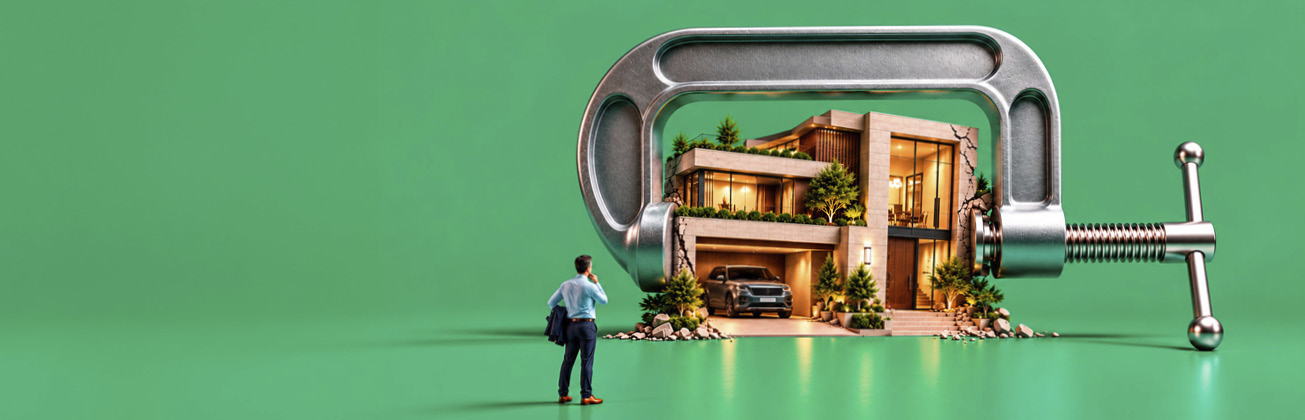
Header image for the October 2026 PYMNTS Intelligence Gen X Playbook. PYMNTS Intelligence finds Gen X faces rising cash flow pressure as savings thin, card balances revolve and more live paycheck to paycheck.

Generation X occupies an unusual position in the United States economy. This cohort of roughly 65 million people, now aged roughly 46 to 61, grew up before the internet, built careers as it arrived and now manages some of the most complicated household balance sheets in the country, paying for college-age children and aging parents while trying to fund retirement inside a 15-year window.

For banks, credit unions, card issuers, lenders and payment providers, Gen X offers a preview of what happens when a high-earning, credit-rich generation runs into sustained cash flow stress. They are not new to digital tools, but they use them selectively, and they carry more revolving credit than any working-age cohort.

“Gen X at the Peak: Why High Earners Are Feeling the Squeeze“ is a PYMNTS Intelligence report publishing in installments. It profiles U.S. consumers born roughly between 1965 and 1980 using proprietary PYMNTS Intelligence surveys, including some collected regularly since 2020. The report covers financial wellbeing, work and employment, income and savings, shopping behavior, payments, technology and AI adoption as well as small business ownership.

This installment covers the financial wellness section. Its headline finding is that the generation with the highest average household spending in the country, nearly $96,000 a year according to the most recent Bureau of Labor Statistics data, has seen its cash flow pressure rise rather than fade. Where millennials have hovered around seven in 10 living paycheck to paycheck since 2020, Gen X has climbed toward that level from a lower starting point.

Get Unlimited Access
Complete the form below for free, unlimited access to all our Data Studies, Trackers, and PYMNTS Intelligence reports.

Thank you for registering. Please confirm your email to view all our Trackers.

    Subscribe to our daily newsletter, PYMNTS Today.

    By completing this form, you agree to receive marketing communications from PYMNTS and to the sharing of your information with our sponsor, if applicable, in accordance with our Privacy Policy and Terms and Conditions.

    Scoping Gen X’s Financial Lifestyle

    About seven in 10 Gen X consumers live paycheck to paycheck. The annual share averaged 70% in 2025, its highest level in six years of tracking, up from 61% in 2021 and 63% in 2023. January 2026 came in at 68%. That is a 14% increase in the paycheck-to-paycheck share between 2021 and 2025 (61% versus 70%), during a period when the millennial share barely moved (71% versus 73%).

    The report’s definition of paycheck-to-paycheck living is not indicative of poverty. PYMNTS Intelligence classifies consumers by whether they struggle to pay bills, manage their pocketbooks despite financial tightness or report no financial pressure at all. In January 2026, 42% of Gen X consumers said they live paycheck to paycheck but pay their bills comfortably, and 26% said they struggle to pay them. A Gen X household annually earning $150,000 with a mortgage, two tuition payments, parents’ care costs and rising insurance premiums can still run out of month before it runs out of bills.

    Why this matters to credit providers

    A Gen X consumer living paycheck to paycheck is very often a prime or super-prime borrower with a mortgage, multiple cards and a retirement account. Three in four Gen X consumers (74%) self-report a prime or super-prime credit score. They may not need more credit. They need products that smooth the timing between when money arrives and when it leaves.

    The data also undercuts the idea that cash flow stress fades with age and income. Gen X’s paycheck-to-paycheck share has risen, not fallen, as it moved deeper into its 50s. That makes the pressure structural rather than a life stage.

    Clearing Up the Savings Picture

    Nearly four in 10 Gen X consumers (38%) have $1,000 or less in readily available savings, including 18% with no savings at all. Another 19% have between $1,001 and $5,000. That means a majority (57%) have $5,000 or less in liquid savings, a slightly larger share than millennials (55%).

    The top end has thinned. The share of Gen X consumers with more than $15,000 in readily available savings was 31% in September 2023 and 26% in January 2026, a 14% decline. This generation still holds more at the top than millennials (26% versus 25%), but far less than baby boomers and seniors (40%).

    That thin cushion shows up when something breaks. More than half of Gen X consumers (54%) paid an unexpected expense of $400 or more in the past 12 months. Of those who did, only one in three (33%) has fully recovered financially, compared with 41% of millennials, a 24% difference, and 28% are still struggling.

    The savings gap flows directly into credit. Gen X consumers who work on gig platforms self-report a subprime score at more than four times the rate of salaried workers (31% versus 7%), and hourly workers at more than three times the rate (24% versus 7%). Two in three salaried Gen X workers (68%) report a super-prime score, versus 40% of hourly workers.

    Gen X’s Income Mix

    Gen X’s income mix looks more like millennials’ than many assume. Among employed Gen X consumers, 43% earn a fixed salary, 40% are paid hourly, 6% work on contract, 4% on commission and 3% earn through gig platforms. The bigger difference is participation. Seventy-one percent of Gen X consumers are employed, compared with 87% of millennials. Fifteen percent are not working and not looking, and 7% are already retired. Working Gen X consumers average $88,785 in personal annual income, roughly 10% more than millennials ($80,545).

    For credit product strategists

    “Gen X” is too broad a category to use on its own. A salaried Gen X homeowner with a super-prime score and five credit cards has little in common with an hourly Gen X worker carrying a revolving balance and $800 in savings. Both are in their 50s. Both may be living paycheck to paycheck. Their needs are different, and the data shows that pay type, not age, is the line that separates them.

    Assessing the Gen X Opportunity

    Gen X consumers hold the most spending power in the country and some of the deepest credit relationships. The challenge is that their cash flow has tightened faster than their financial tools have adapted.

    Providers that help Gen X smooth income timing, rebuild short-term savings and pay down revolving balances without losing rewards can meet a large and growing need. The winning proposition is not “digital,” because Gen X already banks and pays digitally when it makes sense. The more compelling proposition is financial products that treat a prime borrower with thin savings as a cash flow customer, not a credit risk.

    The financial wellness section of The Gen X Playbook series shows a generation with major economic weight but a shrinking margin for error. They are high-value consumers whose financial pressure is rising in what should be their most secure years.

    Read More

    PYMNTS Intelligence is the leading provider of information on the consumer trends driving innovation in consumer finance, digital payments and financial inclusion. To stay up to date, subscribe to our newsletters and read our in-depth reports.

    About

    PYMNTS Intelligence is a leading global data and analytics platform that uses proprietary data and methods to provide actionable insights on what’s now and what’s next in payments, commerce and the digital economy. Its team of data scientists includes leading economists, econometricians, survey experts, financial analysts and marketing scientists with deep experience in the application of data to the issues that define the future of the digital transformation of the global economy. This multilingual team has conducted original data collection and analysis in more than three dozen global markets for some of the world’s leading publicly traded and privately held firms.

    We are interested in your feedback on this report. If you have questions or comments, or if you would like to subscribe to this report, please email us at feedback@pymnts.com.

    Disclaimer

    The Gen X Playbook Series may be updated periodically. While reasonable efforts are made to keep the content accurate and up to date, PYMNTS MAKES NO REPRESENTATIONS OR WARRANTIES OF ANY KIND, EXPRESS OR IMPLIED, REGARDING THE CORRECTNESS, ACCURACY, COMPLETENESS, ADEQUACY, OR RELIABILITY OF OR THE USE OF OR RESULTS THAT MAY BE GENERATED FROM THE USE OF THE INFORMATION OR THAT THE CONTENT WILL SATISFY YOUR REQUIREMENTS OR EXPECTATIONS. THE CONTENT IS PROVIDED “AS IS” AND ON AN “AS AVAILABLE” BASIS. YOU EXPRESSLY AGREE THAT YOUR USE OF THE CONTENT IS AT YOUR SOLE RISK. PYMNTS SHALL HAVE NO LIABILITY FOR ANY INTERRUPTIONS IN THE CONTENT THAT IS PROVIDED AND DISCLAIMS ALL WARRANTIES WITH REGARD TO THE CONTENT, INCLUDING THE IMPLIED WARRANTIES OF MERCHANTABILITY AND FITNESS FOR A PARTICULAR PURPOSE, AND NONINFRINGEMENT AND TITLE. SOME JURISDICTIONS DO NOT ALLOW THE EXCLUSION OF CERTAIN WARRANTIES, AND, IN SUCH CASES, THE STATED EXCLUSIONS DO NOT APPLY. PYMNTS RESERVES THE RIGHT AND SHOULD NOT BE LIABLE SHOULD IT EXERCISE ITS RIGHT TO MODIFY, INTERRUPT, OR DISCONTINUE THE AVAILABILITY OF THE CONTENT OR ANY COMPONENT OF IT WITH OR WITHOUT NOTICE.
    PYMNTS SHALL NOT BE LIABLE FOR ANY DAMAGES WHATSOEVER, AND, IN PARTICULAR, SHALL NOT BE LIABLE FOR ANY SPECIAL, INDIRECT, CONSEQUENTIAL, OR INCIDENTAL DAMAGES, OR DAMAGES FOR LOST PROFITS, LOSS OF REVENUE, OR LOSS OF USE, ARISING OUT OF OR RELATED TO THE CONTENT, WHETHER SUCH DAMAGES ARISE IN CONTRACT, NEGLIGENCE, TORT, UNDER STATUTE, IN EQUITY, AT LAW, OR OTHERWISE, EVEN IF PYMNTS HAS BEEN ADVISED OF THE POSSIBILITY OF SUCH DAMAGES.
    SOME JURISDICTIONS DO NOT ALLOW FOR THE LIMITATION OR EXCLUSION OF LIABILITY FOR INCIDENTAL OR CONSEQUENTIAL DAMAGES, AND IN SUCH CASES, SOME OF THE ABOVE LIMITATIONS DO NOT APPLY. THE ABOVE DISCLAIMERS AND LIMITATIONS ARE PROVIDED BY PYMNTS AND ITS PARENTS, AFFILIATED AND RELATED COMPANIES, CONTRACTORS, AND SPONSORS, AND EACH OF ITS RESPECTIVE DIRECTORS, OFFICERS, MEMBERS, EMPLOYEES, AGENTS, CONTENT COMPONENT PROVIDERS, LICENSORS, AND ADVISERS.
    Components of the content original to and the compilation produced by PYMNTS are the property of PYMNTS and cannot be reproduced without its prior written permission.