October 2026
The Gen X Playbook

Gen X Calls the Cards: What Gets This Generation to Try Something New

Generation X has plenty of ways to pay, yet debit and credit cards funded 81% of its most recent store purchases. Faster payouts reveal an opening for providers: 42% of Gen X payment recipients chose instant receipt for their most recent payout in November 2025. This report explores what keeps cards in front and what gives newer payment options a place in Gen X’s routine.

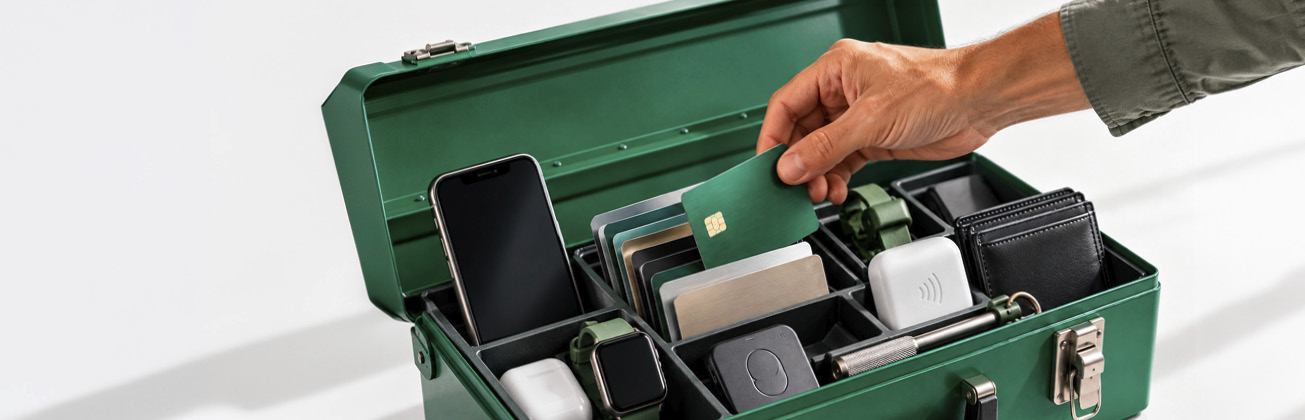
Header image for the October 2026 PYMNTS Intelligence Gen X Playbook, Payments edition. PYMNTS Intelligence reports on Gen X’s use of credit cards, mobile wallets and instant payouts. See what could encourage new payment habits.

Generation X consumers learned to pay with plastic and never stopped using it. They were the first generation to build adult spending habits around credit and debit cards, the first to shop online in large numbers and among the earliest adopters of PayPal. They expect payments to work everywhere, and they have seen enough payment “revolutions” come and go to be wary of changing what already works.

That habit shapes the payments picture. For Gen X, credit and debit cards do most of the work; PayPal fills the online gap; and newer tools such as mobile wallets, buy now, pay later (BNPL), and instant disbursements sit at the edges. Digital options are well within this generation’s reach. They just have not displaced the habits Gen X formed decades ago.

The Gen X Playbook is a PYMNTS Intelligence series profiling U.S. consumers born roughly between 1965 and 1980 using proprietary PYMNTS Intelligence surveys, including some collected regularly since 2020. The report is designed for payments and financial services professionals. It covers Gen X financial well-being, employment, income and savings, shopping behavior, payments, technology and AI adoption, and small business ownership.

This installment, “Gen X Calls the Cards: What Gets This Generation to Try Something New,” focuses on payments. The findings show a generation with a broad but conservative toolkit. Gen X will turn to a mobile wallet, an installment plan or an instant payout when it sees a clear benefit, but cards remain its default, and credit leads overall use.

Get Unlimited Access
Complete the form below for free, unlimited access to all our Data Studies, Trackers, and PYMNTS Intelligence reports.

Thank you for registering. Please confirm your email to view all our Trackers.

    Subscribe to our daily newsletter, PYMNTS Today.

    By completing this form, you agree to receive marketing communications from PYMNTS and to the sharing of your information with our sponsor, if applicable, in accordance with our Privacy Policy and Terms and Conditions.

    Gen X Still Favors Credit Cards

    Ask Gen X how it pays, and the answer is usually a card. Among Gen X consumers who bought retail products in the past 12 months, nearly three in four (74%) paid with a credit card, a 12% higher share than among millennials (66%). Debit followed at 67%, PayPal at 55% and cash at 42%. Gift or prepaid cards (31%) rounded out the top five.

    Gen X consumers used payment methods outside the top five less frequently. Apple Pay led at 20%. Next came Cash App (18%), pay by bank (18%), Google Pay (17%), store cards (17%), BNPL (16%) and Venmo (14%). Shop Pay Installments barely registered at 1%.

    The gap with millennials is widest on newer payment methods. Millennials were 88% more likely than Gen X to have used Apple Pay for retail (37% versus 20%), 98% more likely to have used Cash App (35% versus 18%) and 48% more likely to have used BNPL (23% versus 16%). Among newer methods, the one place this generation leads is pay by bank, where its usage (18%) is slightly ahead of millennials’ (15%).

    Gen X’s reliance on cards is good news for issuers and networks. For FinTechs, wallet and BNPL providers, it’s a reminder that the adoption challenge is conversion, not awareness. This generation has seen the tools but has yet to find a reason to switch.

    How Gen X Pays In-Store

    The in-store picture makes the card advantage even clearer.

    For Gen X consumers’ most recent in-store purchase, debit cards funded 48% of transactions and credit cards 33%. Cash accounted for 9.0%. Together, debit and credit funded 81% of this generation’s store purchases, leaving little room for anything else. Checks (1.0%), BNPL (1.0%) and cryptocurrency (less than 1.0%) barely register.

    Mobile wallets show the same restraint. Only 6.0% of Gen X consumers paid with a mobile wallet on their last store trip, less than half the millennial rate (13%). Fewer than half (48%) have used a mobile wallet for an in-person payment, compared with 70% of millennials, a 45% gap.

    Payment choice reflects habit.

    Access is not the constraint. While 55% of Gen X consumers carry an Apple Pay-capable phone, just 4.0% used Apple Pay for their most recent in-store purchase. When they do reach for a wallet, Apple Pay is the most popular, used by 55%, followed by PayPal (33%) and Google Wallet (25%). The barrier is habit: At the terminal, a card that has worked for 30 years wins by default.

    Banking relationships tell a similar story. Nearly two in three Gen X consumers (63%) hold their primary account at a traditional national, regional or local bank. Another 20% hold theirs at a credit union, a 25% higher share than among millennials (16%). Digital-only banks and FinTechs hold just 14% of Gen X primary accounts, versus 21% for millennials.

    BNPL is also a minority choice for them. Sixteen percent of these consumers made a BNPL payment in the 90 days before January 2026, with the monthly share ranging from 11% to 16% between September 2025 and January 2026. Among millennials, the 90-day share was 21%. For Gen X, installment credit is one tool among several, not a cash flow strategy.

    Gen X and the Speed of Money

    Where they do show appetite for newer payment options is on the receiving side. In November 2025, 42% of Gen X disbursement recipients had a choice and opted for instant receipt. Only 15% had a choice and declined. Another 19% used instant because it was the only option offered.

    The gap between Gen X and millennials is less about preference than access. One in four Gen X recipients (25%) was not offered an instant option at all, compared with 15% of millennials, a 66% gap. Among Gen X consumers receiving income and earnings payouts, where instant is more widely offered, 50% chose instant. Demand rose from 36% of Gen X recipients choosing instant in January 2025 to 42% in May, and it held steady at 42% in November. When the option is there, this generation takes it.

    For banks, card issuers, FinTechs and merchants, these findings point to a practical strategy. Gen X does not need to be sold on digital. It needs a clear reason to change a habit that works: a faster payout, a better reward on the card it already carries or a checkout that removes a step rather than adding one.

    The future of Gen X payments will not be won by replacing the card. It will be won by providers that understand where credit, debit, PayPal, instant payouts and wallets each earn their place. This generation isn’t abandoning familiar methods. It’s deciding, one use case at a time, which new ones deserve a spot beside them.

    Read More

    PYMNTS Intelligence is the leading provider of information on the trends driving innovation in consumer finance, digital payments and financial inclusion. To stay up to date, subscribe to our newsletters and read our in-depth reports.

    About

    PYMNTS Intelligence is a leading global data and analytics platform that uses proprietary data and methods to provide actionable insights on what’s now and what’s next in payments, commerce and the digital economy. Its team of data scientists includes leading economists, econometricians, survey experts, financial analysts and marketing scientists with deep experience in the application of data to the issues that define the future of the digital transformation of the global economy. This multilingual team has conducted original data collection and analysis in more than three dozen global markets for some of the world’s leading publicly traded and privately held firms.

    We are interested in your feedback on this report. If you have questions or comments, or if you would like to subscribe to this report, please email us at feedback@pymnts.com.

    Disclaimer

    The Gen X Playbook Series may be updated periodically. While reasonable efforts are made to keep the content accurate and up to date, PYMNTS MAKES NO REPRESENTATIONS OR WARRANTIES OF ANY KIND, EXPRESS OR IMPLIED, REGARDING THE CORRECTNESS, ACCURACY, COMPLETENESS, ADEQUACY, OR RELIABILITY OF OR THE USE OF OR RESULTS THAT MAY BE GENERATED FROM THE USE OF THE INFORMATION OR THAT THE CONTENT WILL SATISFY YOUR REQUIREMENTS OR EXPECTATIONS. THE CONTENT IS PROVIDED “AS IS” AND ON AN “AS AVAILABLE” BASIS. YOU EXPRESSLY AGREE THAT YOUR USE OF THE CONTENT IS AT YOUR SOLE RISK. PYMNTS SHALL HAVE NO LIABILITY FOR ANY INTERRUPTIONS IN THE CONTENT THAT IS PROVIDED AND DISCLAIMS ALL WARRANTIES WITH REGARD TO THE CONTENT, INCLUDING THE IMPLIED WARRANTIES OF MERCHANTABILITY AND FITNESS FOR A PARTICULAR PURPOSE, AND NONINFRINGEMENT AND TITLE. SOME JURISDICTIONS DO NOT ALLOW THE EXCLUSION OF CERTAIN WARRANTIES, AND, IN SUCH CASES, THE STATED EXCLUSIONS DO NOT APPLY. PYMNTS RESERVES THE RIGHT AND SHOULD NOT BE LIABLE SHOULD IT EXERCISE ITS RIGHT TO MODIFY, INTERRUPT, OR DISCONTINUE THE AVAILABILITY OF THE CONTENT OR ANY COMPONENT OF IT WITH OR WITHOUT NOTICE.
    PYMNTS SHALL NOT BE LIABLE FOR ANY DAMAGES WHATSOEVER, AND, IN PARTICULAR, SHALL NOT BE LIABLE FOR ANY SPECIAL, INDIRECT, CONSEQUENTIAL, OR INCIDENTAL DAMAGES, OR DAMAGES FOR LOST PROFITS, LOSS OF REVENUE, OR LOSS OF USE, ARISING OUT OF OR RELATED TO THE CONTENT, WHETHER SUCH DAMAGES ARISE IN CONTRACT, NEGLIGENCE, TORT, UNDER STATUTE, IN EQUITY, AT LAW, OR OTHERWISE, EVEN IF PYMNTS HAS BEEN ADVISED OF THE POSSIBILITY OF SUCH DAMAGES.
    SOME JURISDICTIONS DO NOT ALLOW FOR THE LIMITATION OR EXCLUSION OF LIABILITY FOR INCIDENTAL OR CONSEQUENTIAL DAMAGES, AND IN SUCH CASES, SOME OF THE ABOVE LIMITATIONS DO NOT APPLY. THE ABOVE DISCLAIMERS AND LIMITATIONS ARE PROVIDED BY PYMNTS AND ITS PARENTS, AFFILIATED AND RELATED COMPANIES, CONTRACTORS, AND SPONSORS, AND EACH OF ITS RESPECTIVE DIRECTORS, OFFICERS, MEMBERS, EMPLOYEES, AGENTS, CONTENT COMPONENT PROVIDERS, LICENSORS, AND ADVISERS.
    Components of the content original to and the compilation produced by PYMNTS are the property of PYMNTS and cannot be reproduced without its prior written permission.