Credit unions have already earned their members’ trust. Giving those members more reasons to use their cards could start with something tangible: rewards on everyday purchases.
That opportunity anchors the third key finding in “The Top-of-Wallet Challenge: Why Trust Alone Is Not Enough to Drive Card Usage,” a July 2026 Credit Union Tracker® from PYMNTS Intelligence done in collaboration with Velera. The report finds that strong relationships and high satisfaction haven’t consistently made credit union cards members’ first choice. Rewards offer a practical way to close that gap. Trust gives credit unions a seat at the table; card benefits help them win the next purchase. For institutions seeking more member spending, the findings point toward improving the value members receive each time they pay.
We’d love to be your preferred source for news.
Please add us to your preferred sources list so our news, data and interviews show up in your feed. Thanks!
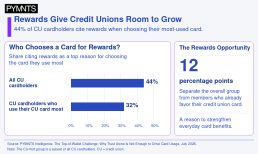
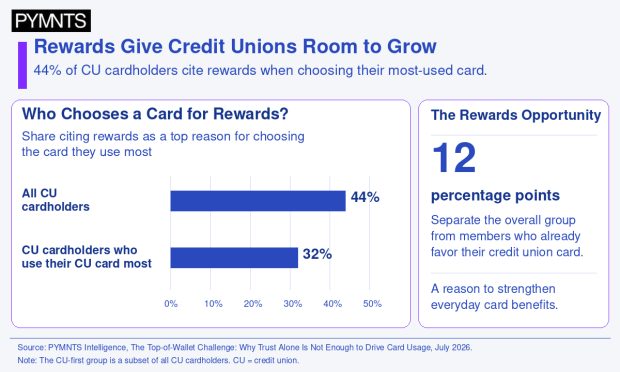
- Rewards influence 44% of credit union cardholders’ choices. That share cites rewards as a top reason for selecting the card they use most. Among cardholders who already use their credit union card most, the figure is 32%, a difference of 12 percentage points. The comparison suggests credit unions have an opportunity to appeal to members whose payment decisions depend more heavily on rewards. Members who already favor their credit union card place greater value on contactless payments, visibility into spending across accounts and customer service. Those strengths provide a starting point for broader card programs.
- Credit unions trail national banks by 21 percentage points in becoming cardholders’ first choice. Credit unions convert 48% of consumer cardholders into users who put their cards first, compared with 69% for national banks. That difference persists even though 61% of consumer members consider their credit union their primary financial institution. A primary banking relationship doesn’t automatically determine which card someone chooses at checkout. The opportunity is to connect that existing relationship with benefits members can readily recognize and use.
- Better rewards could prompt 41% of consumers to promote a secondary card. Mastercard research cited in the report finds that these consumers would move a secondary card into first position for stronger rewards and benefits. The finding suggests payment preferences can change. Credit unions can tailor their approach: younger members seek rewards connected to financial goals, while small-business members who favor another institution’s card lean toward budgeting and expense-management tools.
Other findings show credit unions have substantial strengths to build on. Among consumers whose primary institution is a credit union, 87% report being very or extremely satisfied. Credit union cards also lead national bank cards for utility bills, at 37% versus 34%, and internet and mobile service, at 35% versus 33%. Pairing those established payment relationships with relevant rewards could help credit unions earn more everyday purchases.
At PYMNTS Intelligence, we work with businesses to uncover insights that fuel intelligent, data-driven discussions on changing customer expectations, a more connected economy and the strategic shifts necessary to achieve outcomes. With rigorous research methodologies and unwavering commitment to objective quality, we offer trusted data to grow your business. As our partner, you’ll have access to our diverse team of PhDs, researchers, data analysts, number crunchers, subject matter veterans and editorial experts.


 Add as Preferred Source