Agentic commerce is becoming an infrastructure race. The biggest agentic constraint today is not whether AI can shop but whether the systems surrounding that AI can determine what an agent is allowed to do, who is responsible when something goes wrong and how a machine-initiated transaction moves safely across merchants, banks and payment networks.
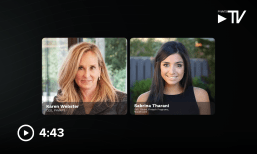
“We don’t see this so much as a new channel, as much as a new interface for interacting and engaging with commerce,” Sabrina Tharani, senior vice president, Global Fintech Programs at Mastercard, said in a conversation hosted by PYMNTS CEO Karen Webster.
That is shifting the competitive battleground beneath the chatbot.
“The first real mainstream adoption of agentic transactions is going to be low-value but high-frequency purchases, where consumers are prioritizing speed and convenience over everything else,” Tharani said, adding that Mastercard announced a 22-company agentic commerce and services cohort through Start Path, its startup engagement program.
The implication is that agentic commerce will not arrive as a wholesale replacement for conventional shopping. It will expand from areas where consumers already tolerate automation into transactions requiring progressively greater levels of trust.
The First Agentic Transactions Will Look Like Boring Ones
Much of the agentic commerce debate has focused on the endpoint: autonomous software capable of searching, comparing, negotiating and buying on behalf of a consumer. The more useful question is what consumers will delegate first.
Tharani reiterated the benefits agentic can bring to recurring payments, household staples and eventually seasonal purchasing moments such as back-to-school and holiday shopping. These are categories where the cost of a bad decision is relatively low and the value of saving time is relatively high. They are also behaviors consumers have already partially automated through subscriptions, saved carts and recurring orders.
“For me, I’m very happy to hand over the reins as it relates to browsing and recommendations, price comparison, and learning about new spaces that agents recommend to me,” Tharani said, while adding that purchasing authority remains a higher bar.
Agentic commerce, after all, does not need to jump directly from search to autonomous purchasing. Delegation can move gradually through the transaction funnel.
The challenge is that each additional degree of autonomy increases the importance of infrastructure surrounding the agent. Webster described the desired end state as an experience in which the entire transaction can happen without forcing consumers to move between interfaces.
We’d love to be your preferred source for news.
Please add us to your preferred sources list so our news, data and interviews show up in your feed. Thanks!
“I’ve discovered, I’ve ranked, I’ve compared. Now I can pay and I can get it delivered and then I can, if there’s a problem, I know how to resolve that,” she said.
The final clause is critical. Agentic commerce is not solved when an AI can successfully press “buy.” It is solved when the broader commerce system can manage everything that follows.
The AI Agent Is No Longer the Hardest Part. Control and Liability Are.
For an agentic transaction to work consistently, merchants need to recognize agents. Financial institutions need to know what permissions those agents have. Payment systems need to authenticate credentials and enforce limits, while loyalty programs need to determine whether benefits still apply. Crucially, consumers need recourse if an autonomous decision produces the wrong result.
Those are not primarily AI challenges. They are commerce infrastructure challenges.
“It’s not just about the agent itself. It’s about the infrastructure that underpins what these economies are going to look like,” Tharani said.
The underlying networks, merchants, bank accounts and credentials may remain familiar. What changes is the layer interacting with them. That framing places agentic commerce in a longer sequence of interface changes. The internet changed where consumers shopped. Smartphones changed how they accessed payments and commerce. AI agents could change who, or what, carries the consumer’s intent into the transaction.
For Mastercard, that means looking beyond compelling technology demonstrations toward whether startups can operate at network scale. Tharani said the company evaluates founding teams, funding, technology and global expansion potential, including whether a startup operating in one market could scale into others through Mastercard’s ecosystem.
The emerging contest in agentic commerce, in other words, may be more about infrastructure than intelligence.
Watch the full PYMNTS TV interview with Mastercard’s Sabrina Tharani to hear more about:
- Why agentic commerce will likely go mainstream through boring purchases first. Tharani says low-value, high-frequency transactions such as household staples, recurring payments and seasonal shopping offer consumers an easier path from automation to delegation.
- Why discovery is moving faster than purchasing autonomy. Tharani says consumers are already comfortable handing AI browsing, recommendations and price comparison, but most still stop short of giving agents full authority to buy.
- Why the agent may no longer be the hardest part of agentic commerce. Tharani and Webster point to trust, identity, payments, merchant enablement and post-purchase resolution as the infrastructure that must work together before AI can reliably complete transactions at scale.


 Add as Preferred Source