Digital bank customers are more willing than the broader banking population to move transactions to Pay by Bank when the payment method comes with discounts and buyer protection, according to PYMNTS Intelligence research.
The findings come from “Pay by Bank Deep Dive: Digital Bank Users Are Ready to Switch,” a PYMNTS Intelligence report produced in collaboration with Trustly. The study is based on a U.S. Census-balanced survey of 2,071 adult U.S. bank customers. It examines consumers’ interest in and willingness to use Pay by Bank.
Three findings show where the opportunity is strongest:
We’d love to be your preferred source for news.
Please add us to your preferred sources list so our news, data and interviews show up in your feed. Thanks!
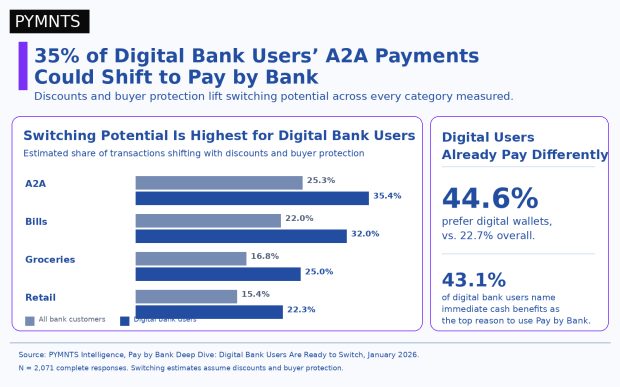
- 35.4% of digital bank users’ account-to-account transactions could shift to Pay by Bank if discounts and buyer protection were offered, compared with 25.3% for the full sample. For bill payments, the estimates are 32% for digital bank users and 22% overall.
- Digital bank users also show higher switching potential for everyday purchases. The estimated share reaches 25% for groceries, versus 16.8% for the full sample, and 22.3% for retail, versus 15.4%.
- 44.6% of digital bank customers prefer digital wallets as a payment method, nearly double the 22.7% share for the full sample. Debit cards rank second among digital bank users at 29.6%, while just 10.1% prefer credit cards.
Digital bank customers already stand apart in how they pay. Wallets are their leading choice for retail purchases, subscriptions, rideshare and account-to-account transactions. For example, 51.9% prefer wallets for rideshare, 47.3% for A2A transactions and 43% for subscriptions.
The report also finds that the incentives most likely to drive Pay by Bank use do not differ much by bank type. Among digital bank users, 43.1% name immediate cash benefits as the most important reason to use Pay by Bank, while 16.9% cite buyer protection. About one-quarter, 25.4%, say none of the listed incentives would make them more interested.
Pay by Bank still has ground to cover as a debit alternative. Only 12.2% of all bank customers currently view it as a substitute for debit. With rewards, buyer protection or both added, however, the report says 72% either already see Pay by Bank as a debit substitute or would do so under at least one of those conditions.
Digital bank users combine greater comfort with digital payment experiences and higher estimated switching potential across every transaction category measured. The data indicates that discounts and purchase protections are central to converting that openness into transaction volume.
At PYMNTS Intelligence, we work with businesses to uncover insights that fuel intelligent, data-driven discussions on changing customer expectations, a more connected economy and the strategic shifts necessary to achieve outcomes. With rigorous research methodologies and unwavering commitment to objective quality, we offer trusted data to grow your business. As our partner, you’ll have access to our diverse team of PhDs, researchers, data analysts, number crunchers, subject matter veterans and editorial experts.


 Add as Preferred Source